

A lump sum on your turn
An early turn can give you access to the pooled sum before you could save that amount alone. The order must be agreed; an early turn is not available to everyone. You keep contributing after your draw.
How PardnerPlus works
Starting a small business can mean finding money for your first stock, tools or opening costs. A Pardner pools regular contributions into a draw for each member in turn. PardnerPlus helps your group agree the timing, commitments and shared record.
PardnerPlus keeps the shared plan and record clear while your group stays in control of its contribution arrangements.
A Pardner in 20 seconds
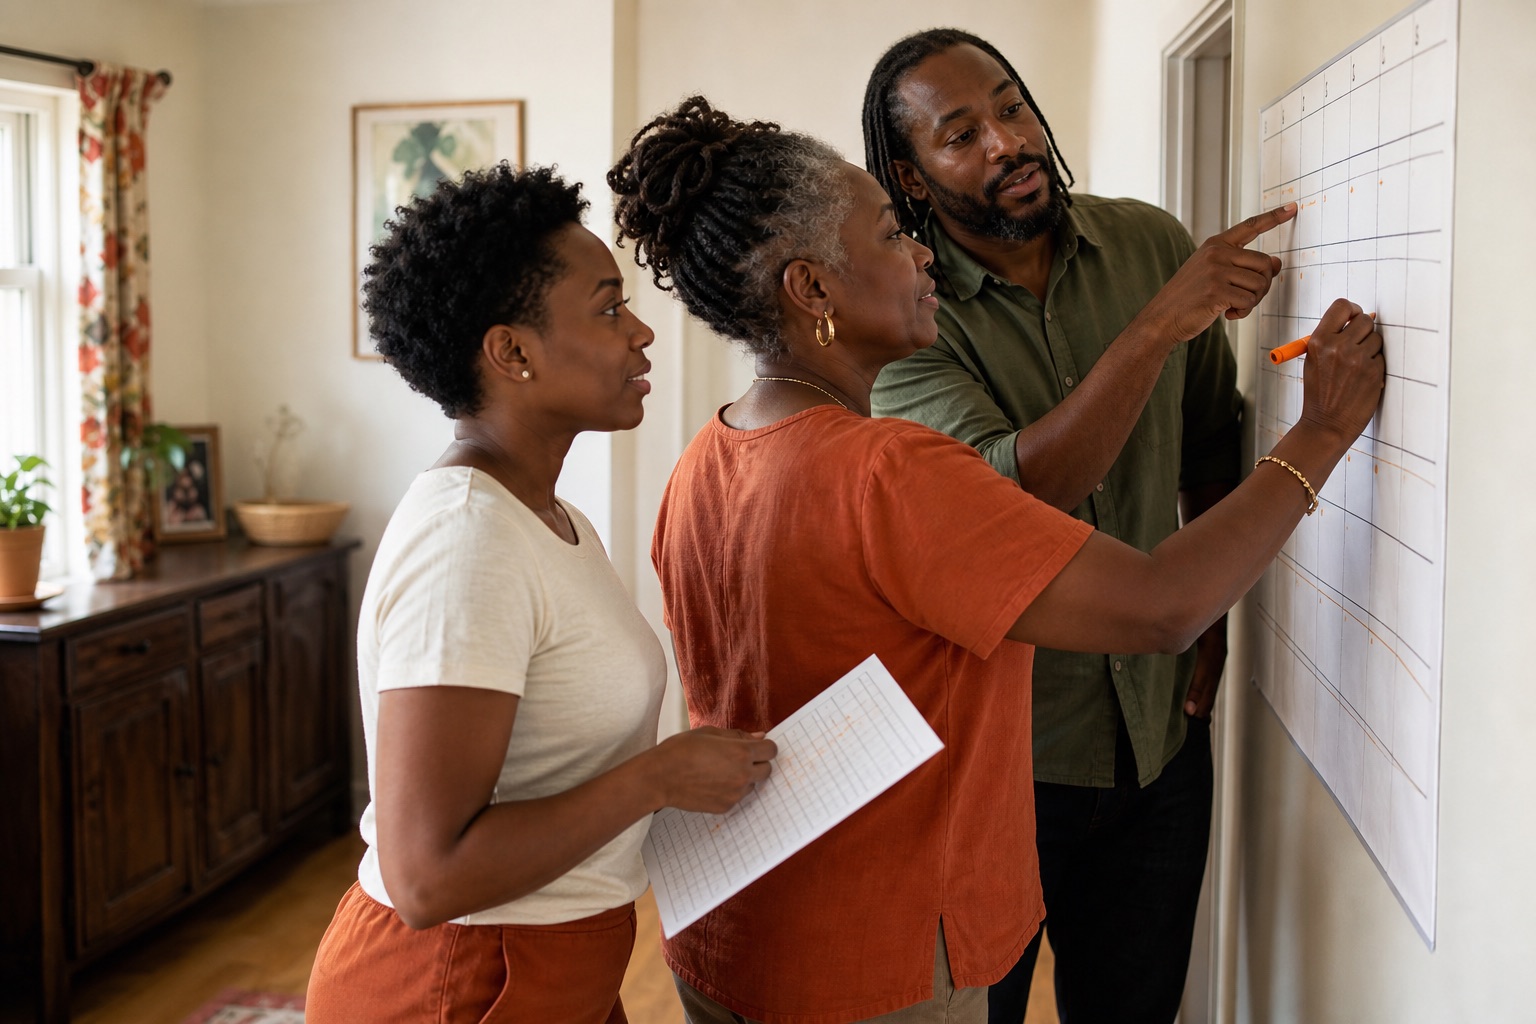
The group agrees the hand, timing and draw order before starting. Your group chooses and controls its payment arrangements; PardnerPlus keeps the shared plan and record clear.
Each member pays the agreed hand at the agreed time.
One member receives the planned Pardner draw for that turn.
The agreed contributions continue until every planned turn is complete.
In Jamaica, it is Pardner. Related traditions may be called Partner, Pardna, Su Su, Box Hand, Tanda or Hui. Names and customs vary by community.
Explore our roots and stories →A simple example
If everyone contributes £100 on each of four weekly turns, the planned draw is £400 per turn. Each person contributes £400 over the cycle and receives one £400 draw. This example excludes fees and any additional buffer; it does not create profit or guarantee a payout.
Why save together?
Timing and a shared commitment can make a difference when you are building the money to start a small business. A Pardner can sit alongside your bank account.
An early turn can give you access to the pooled sum before you could save that amount alone. The order must be agreed; an early turn is not available to everyone. You keep contributing after your draw.
An agreed schedule can help you keep working towards the first stock, tools or training you need. A later turn mainly provides structured saving, without the same early-access benefit.
Bank savings may offer interest, flexible withdrawals depending on the account, and eligible deposit protection. A traditional informal Pardner has different risks: missed contributions can affect the draw, access follows the agreed turn, and bank-style protection must not be assumed.
Before joining, check who handles the money, every fee, the draw order and what happens if someone misses a contribution. Choose a commitment you can maintain even if a new business takes time to earn money.
Questions before you join →No. A Pardner pools the group’s contributions and follows an agreed draw order. Your access to the pot depends on your turn. Do not assume bank-style deposit protection; check the actual payment arrangements.
No. With four people paying £100 weekly for four weeks, the first person can receive £400 in week one, then owes £100 in each of the next three weeks. This is pooled money, not £300 profit.
It can delay or reduce the money available for a draw. Before joining, agree who handles payments, the fees, the missed-payment process and what happens if you need to leave.
Check who is in the group, read the full rules and choose an amount you can keep paying without borrowing or missing essential bills. Ask questions before you accept.
The Pardner, step by step
Invite people you know and trust. Decide who will organise the group and who will take part.
Set the hand, frequency, start date, draw order and what happens if somebody is late.
Members review the same plan before joining, so expectations are visible rather than assumed.
Keep a shared history of scheduled contributions, confirmed activity and upcoming turns.
The group follows its agreed payment arrangement while PardnerPlus keeps every turn and Pardner draw clear.
Put the planned lump sum toward a goal—or independently explore third-party saving and investment options.
Why is it called PardnerPlus?
A Pardner already creates discipline and a planned draw. PardnerPlus adds a clearer shared plan, visible progress and useful paths for what you want to achieve next.
See the next contribution, the next turn and the shared decisions without chasing scattered messages.
Picture the relief of reaching a deposit, buying business equipment or paying for a course at the moment you planned.
Use the draw for your goal, or independently compare third-party saving and investment providers when the timing is right.
Start a small business
Price the stock, tools or essential start-up costs needed to serve your first customers. Compare that budget with your planned draw and keep room for the contributions you still owe. Training, housing and family trips are other useful goals; a draw does not guarantee business success.
Plan what your draw could make possible →If a member wants to invest afterwards, the Investment Directory can introduce independent third-party providers. Their products, permissions, risks and returns remain their responsibility.
Explore the Investment Directory →Your group remains responsible for its money arrangements